By Thomas Whitfield · Contributing Writer
Published · Updated
Answer in brief
Miami-Dade County carries the highest car insurance premiums in Florida and some of the highest in the country. Full coverage for a typical adult driver frequently exceeds $4,000 a year. Dense traffic, high crash and theft frequency, a large uninsured population and persistent injury litigation all feed the rate. Miami drivers benefit most from stacked UM, higher deductibles, telematics and aggressive comparison, because base rates differ sharply between insurers in this territory.
Why Miami rates are what they are
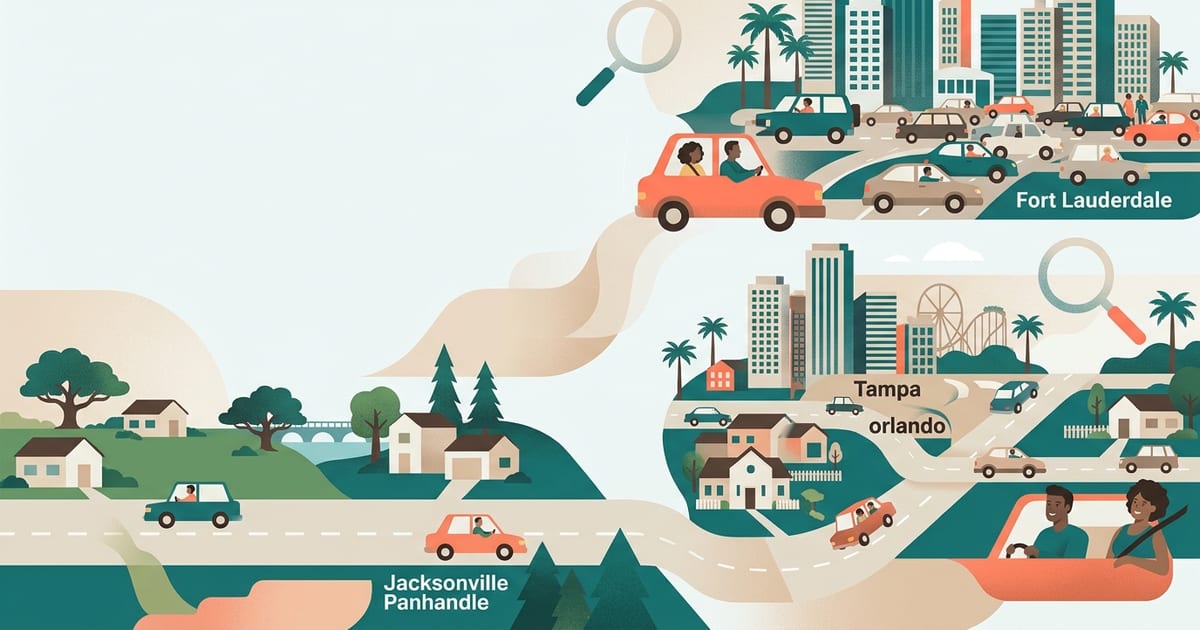
Miami-Dade combines nearly every cost driver in one territory: more than two and a half million residents and heavy tourist traffic on a constrained road network; elevated vehicle theft; a high proportion of uninsured and minimum-coverage drivers; and a long history of PIP and injury litigation. Insurers price all of that into base rates before looking at your record.
What Miami drivers can control
- Carry stacked UM; the uninsured population makes it essential.
- Use $1,000 deductibles on a high base rate for a larger dollar saving.
- Try telematics—highway commuters often score well despite the city's reputation.
- Garage the car where possible; theft and vandalism drive comprehensive costs.
- Compare at every renewal; the spread between insurers in Miami-Dade is the widest in the state.
The broader context is in the by-city guide and the average cost guide.
Terms: Rating territory, Stacked UM
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Fla. Stat. § 627.736 — required personal injury protection benefits — Florida Legislature (Online Sunshine), Fla. Stat. § 627.736Primary lawPIP: $10,000 medical and disability benefits, $5,000 death benefit; 80% of reasonable medical expenses, 60% of lost income; initial care within 14 days; $2,500 cap without an emergency medical condition.
- Fla. Stat. § 324.022 — property damage liability requirement — Florida Legislature (Online Sunshine), Fla. Stat. § 324.022Primary lawEvery owner must maintain at least $10,000 property damage liability (or a $30,000 combined single limit with PIP).
- Facts + Statistics: Uninsured motorists — Insurance Information Institute (2024)Statistical dataInsurance Research Council estimates of uninsured drivers by state (2022: e.g. Michigan 19.6%, California 17.0%, Florida 15.9%, Texas 13.8%).
- Insurance losses by make and model — Highway Loss Data InstituteStatistical dataRelative claim frequency and severity by vehicle under collision, property damage, comprehensive, PIP, MedPay and bodily injury coverages.
- What determines the price of an auto insurance policy? — Insurance Information InstituteConsumer guidanceRating factors: driving record, mileage, location, age, gender, vehicle, credit-based insurance score, coverage choices. Notes ZIP-code rating is prohibited in California and Michigan and gender rating is prohibited in seven states.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.
Entry
Car Insurance in Orlando
Orlando car insurance costs sit near the Florida average. What drives rates in Orange County and how to compare quotes locally.
Entry
Car Insurance in Tampa
Tampa Bay car insurance costs, the I-275 and Gandy corridors, storm surge exposure, and how Hillsborough and Pinellas rates compare.
Entry
Car Insurance in Jacksonville
Jacksonville has some of the lowest car insurance costs among Florida's large cities. Why Duval County is cheaper and what still matters.
Parent guide
Car Insurance Rates by City in Florida
How car insurance costs differ across Florida cities, from Miami and Fort Lauderdale to Jacksonville, Tampa, Orlando and the Panhandle.