By Thomas Whitfield · Contributing Writer
Published · Updated
Answer in brief
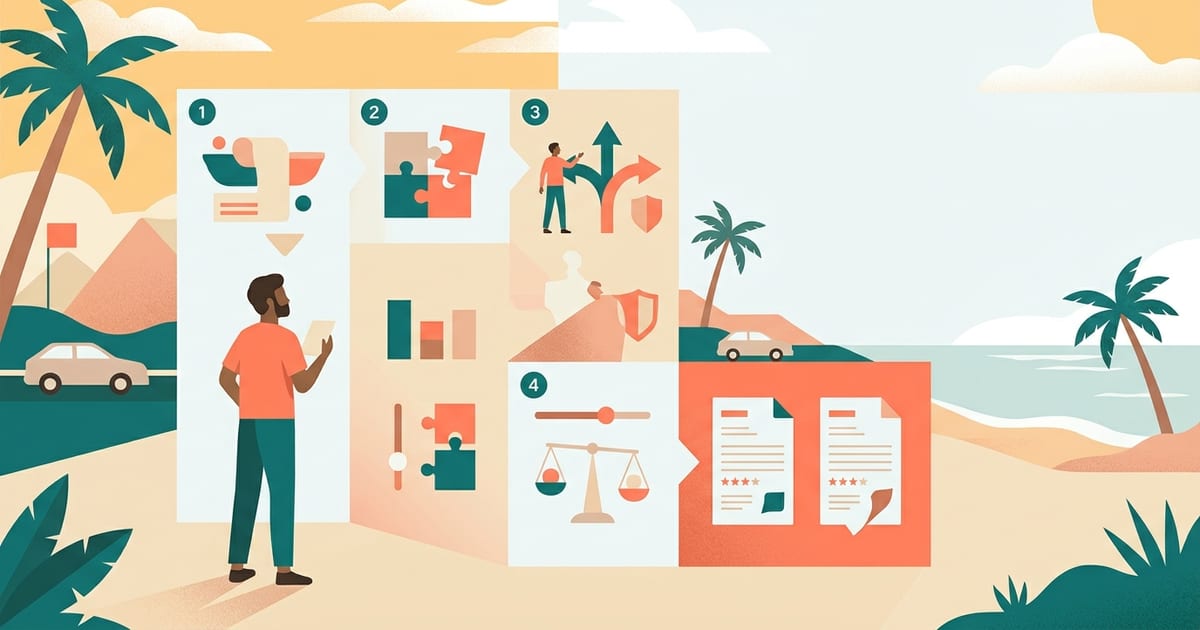
Comparing Florida quotes is only useful when every quote prices the same coverage set: identical BI and PD limits, the same PIP options (deductible, work-loss exclusion), the same UM choice (stacked or not), the same collision and comprehensive deductibles and the same drivers and vehicles. Fixing those first, then gathering at least three quotes, routinely uncovers differences of $500–$1,500 a year for the same Florida driver because insurers weight territory, credit and record differently.
Step 1: Fix the coverage set
Write down one set of coverages and use it for every quote. A reasonable Florida default for an owned car worth $10,000 or more: BI 50/100, PD $50,000, PIP $10,000 with no deductible, stacked UM 50/100, collision and comprehensive with $1,000 deductibles. Adjust to your situation, but do not let each insurer's form push you into a different set.
Step 2: Know the Florida-specific toggles
- PIP deductible ($250–$1,000) lowers premium but comes out of a benefit that is already small.
- Work-loss exclusion on PIP saves a little if you have no income to protect (retirees, students).
- Stacked vs non-stacked UM—see the UM guide.
- Glass coverage—some Florida policies include zero-deductible windshield replacement.
Step 3: Gather at least three quotes
Use a comparison tool to get several at once, plus one or two direct. Enter the same garaging address, the same annual mileage and the same drivers each time—small changes in inputs produce large changes in price and make comparisons meaningless.
Step 4: Compare the total cost
Add installment fees, policy fees and any FR-44/SR-22 filing fee to the premium. A lower headline premium with a $10 monthly installment fee can cost more than a slightly higher pay-in-full price. Check the policy term as well—six-month and twelve-month policies look different side by side.
- 1
Set the coverage
One list of limits and deductibles for every quote.
- 2
Collect quotes
Three to five, same inputs, same day.
- 3
Normalise
Annual total including fees.
- 4
Check filings and service
Confirm FR-44/SR-22 capability if needed; read cancellation terms.
- 5
Bind before cancelling
Start the new policy before the old one ends to avoid a lapse.
Quote finder
Find auto insurance quotes that fit your situation
Questions & answers
How often should I compare car insurance in Florida?
At every renewal, and any time something changes—new address, new car, a ticket aging off, a driver added or removed.
Does getting quotes hurt my credit?
Insurance quotes use a soft inquiry that does not affect your credit score.
Is the cheapest quote the best?
Only if it is for the same coverage and from an insurer whose claims handling and fees you have checked.
Terms used in this guide
- Premium
- The price you pay for a policy, usually quoted per six or twelve months.
- Deductible
- The amount you pay before collision or comprehensive pays. Higher deductibles lower premiums, with larger dollar savings on Florida's high base rates.
- Stacked UM
- An option that multiplies your UM limit by the number of vehicles on the policy. Two cars with 100/300 stacked UM give $200,000 per person.
- Personal injury protection (PIP)
- Florida's required no-fault coverage. Pays 80% of your medical expenses and 60% of lost wages after a crash, regardless of fault, up to $10,000.
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- Fla. Stat. § 627.736 — required personal injury protection benefits — Florida Legislature (Online Sunshine), Fla. Stat. § 627.736Primary lawPIP: $10,000 medical and disability benefits, $5,000 death benefit; 80% of reasonable medical expenses, 60% of lost income; initial care within 14 days; $2,500 cap without an emergency medical condition.
- Fla. Stat. § 324.022 — property damage liability requirement — Florida Legislature (Online Sunshine), Fla. Stat. § 324.022Primary lawEvery owner must maintain at least $10,000 property damage liability (or a $30,000 combined single limit with PIP).
- 2019–2023 Auto Insurance Database: average premium supplement — National Association of Insurance Commissioners (2025)Statistical dataCountrywide average expenditure $1,281 in 2023 (+13.98%); combined average premium $1,438; state tables for liability, collision and comprehensive.
- Facts + Statistics: Auto insurance — Insurance Information Institute (2025)Statistical dataNAIC countrywide average auto expenditure: $1,127 (2022), $1,282 (2023); most expensive states in 2023 were Florida, Louisiana and New York.
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
- How much auto coverage do I need? — Insurance Information InstituteConsumer guidanceWhy state minimums are a floor; choosing liability limits that protect assets; when collision and comprehensive are worth keeping.
- Insurance research and advocacy — Consumer Federation of AmericaConsumer guidanceConsumer-side research on auto insurance pricing, non-driving rating factors and affordability.
- Consumer insurance information — National Association of Insurance CommissionersConsumer guidancePlain-language guides from the body of state insurance regulators; links to every state's insurance department and complaint process.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.
Guide
Average Cost of Car Insurance in Florida
Why Florida has some of the highest auto insurance premiums in the country, how costs vary by city and driver, and what moves the number.
Guide
Car Insurance Discounts in Florida
The discounts Florida insurers commonly offer—telematics, bundling, defensive driving, good student, pay-in-full—and which actually move the premium.
Guide
Full Coverage Car Insurance in Florida
What full coverage means in Florida, when you need it, how to choose deductibles, and how hurricane season affects comprehensive coverage.